YES BANK POP-CLUB Credit Card: POPcoins, Fees and Eligibility (2026)
YES BANK POP-CLUB credit card explained: nil joining fee, ₹399 renewal and its ₹1.5 lakh waiver, POPcoins earn rates, exclusions, charges and eligibility, from YES BANK’s own pages.
Thinking about the YES BANK POP-CLUB credit card? It is a co-branded RuPay card that YES BANK issues with the fintech POP, and its rewards come as POPcoins that you spend inside the POPclub app and on POP’s partner brands. You can’t apply on the YES BANK website itself: the bank’s page says you apply through the partner’s website or mobile app, and that the partner may charge a platform fee for its own services.
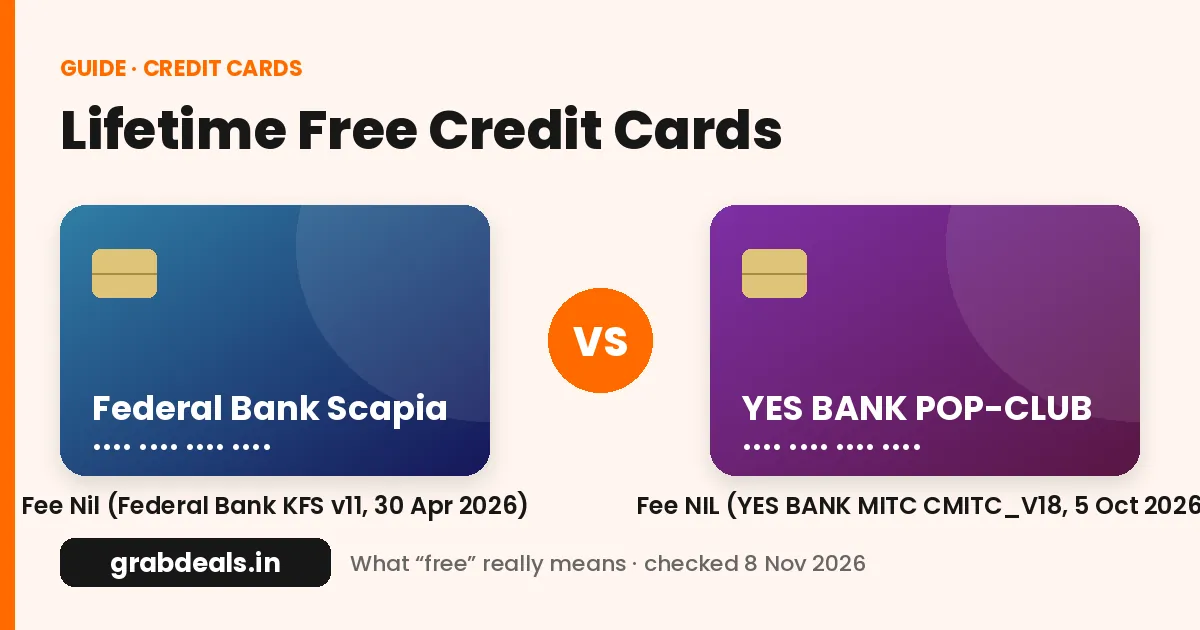
We read YES BANK’s POP-CLUB product page (benefits, eligibility, fees, FAQs and terms) and the bank’s credit-card Most Important Terms and Conditions (document CMITC_V18_05102026) on 14 Nov 2026. Every fee, earn rate and rule below comes from those two sources, which are linked at the end. We haven’t been issued this card ourselves, and this is not financial advice. For other options, see our credit cards page and our guide to what lifetime free credit cards really cost.
Quick answer
Good fit if most of your card spend is online and you will actually redeem POPcoins in the POPclub app: YES BANK lists 10 POPcoins per ₹100 on e-commerce/online spends and 2 per ₹100 on other spends including UPI, with nil joining fee. The renewal fee is ₹399 + taxes, not charged if you cross ₹1.5 lakh spend in the anniversary year (and not applicable at all if your card is issued under the limited-time Lifetime Free offer). Skip it for foreign spends (3.50% mark-up) and for rent, fuel, wallet, utility, insurance, education and EMI spends, which earn no POPcoins. Approval and final terms are decided by YES BANK.
YES BANK POP-CLUB Credit Card
YES BANK
10 POPcoins per ₹100 online and 2 per ₹100 on other spends including UPI (RuPay), per YES BANK’s product page
- Joining fee
- Nil
- Annual fee
- ₹399 + taxes (not charged after ₹1.5 lakh spend in the anniversary year; not applicable to Lifetime Free cards)
- Forex markup
- 3.50% (MITC, effective 15 Jun 2026)
Best for: Online shoppers who already use POPclub partner brands and want a RuPay card for UPI. YES BANK decides approval, limit and terms.
Apply NowApproval, limit and final terms are decided by the bank.
POP-CLUB card at a glance
| What YES BANK lists | |
|---|---|
| Network | RuPay (credit on UPI) |
| Joining fee | Nil (“Zero joining fees”) |
| Annual / renewal fee | ₹399 + applicable taxes; charged only if the spend condition is not met; not applicable for Lifetime Free cards |
| Fee waiver spend | ₹1,50,000 in the anniversary year |
| Online earn | 10 POPcoins per ₹100 on e-commerce / online spends |
| Other spends incl. UPI | 2 POPcoins per ₹100 |
| Milestone | Extra 1,500 POPcoins on crossing ₹1.5 lakh spend in an anniversary year |
| POPcoin expiry | 365 days from the date of credit |
| Interest | 3.99% a month (47.88% a year) |
The product page also headlines “Lifetime Free (Limited time offer)”. That matters because two versions of this card exist on paper: one issued under the Lifetime Free offer, and one on the standard ₹399 schedule. The page itself says the annual fee is “Not Applicable for Life Time Free Card”, and the MITC repeats that joining and annual fees don’t apply to Lifetime Free cards. Which version you get is shown in the application journey and your welcome documents, so check that before you assume the card will always be free.
The page also lists partner perks: a 3-month Zomato Gold Mini membership, a 6-month PharmEasy Plus membership and a Cleartrip voucher worth ₹750. It marks these with an asterisk, so the claim steps and conditions sit with POP and its partners. Read them in the app before you count them as value.
How POPcoins work
YES BANK describes POPcoins as a loyalty currency used on the POPclub website, the POPclub app and POP’s brand-partner websites. The FAQ on the product page adds four practical rules:
- The minimum transaction to earn POPcoins is ₹100.
- POPcoins are credited after your monthly credit card statement is generated, not instantly.
- POPcoins expire 365 days (one year) after they are credited.
- POPcoins are given only on personal spends.
| Spend type | POPcoins (YES BANK page) | Example: ₹10,000 spend |
|---|---|---|
| E-commerce / online | 10 per ₹100 | 1,000 POPcoins |
| Other spends, including UPI | 2 per ₹100 | 200 POPcoins |
| Crossing ₹1.5 lakh in an anniversary year | +1,500 one-time | Bonus at the milestone |
| Paying the ₹399 annual fee | 400 POPcoins | Credited when the fee is paid |
What is a POPcoin worth?
This is the part people skip. YES BANK’s page doesn’t publish a fixed rupee value for a POPcoin. It sends you to POP for details, and redemption happens on POPclub and partner brands. So the “10 per ₹100” headline only turns into real savings if the brands you already buy from accept POPcoins at a value that makes sense to you. Before you move a big monthly spend to this card, open the POPclub app and see what your coins actually buy. Also remember the 365-day expiry: coins you don’t use within a year are lost.
What earns no POPcoins
The terms on YES BANK’s product page say POPcoins are not given on fuel, rent, wallet loads, government and marketing/advertising category transactions, ATM withdrawals, utility, insurance premiums, POI funding transactions, or transactions converted into EMI. With effect from 1 June 2026, education transactions were added to that list. The page lists indicative merchant category codes, for example 6513 for rent, 6540 for wallet loads, 4900 for utilities and 6300 for insurance, and notes that MCCs are set by the card network, not by the bank.
Two more limits are worth knowing. Only five rent transactions are allowed in any 30 days. And because the card runs on RuPay, many people will use it for UPI. That is allowed, but UPI spends fall in the 2-per-₹100 bucket, not the 10-per-₹100 online bucket. If most of your spend is scan-and-pay at local shops, the headline rate isn’t the rate you will see.
Fees and charges from the YES BANK MITC
| Charge | What the MITC lists |
|---|---|
| Interest-free period | Up to 50 days (only if the previous statement was paid in full) |
| Finance charges | 3.99% a month (47.88% a year) on revolving credit, cash advances and overdue amounts |
| Late payment | Nil if the current outstanding is up to ₹500; above that, 10% of the statement balance or ₹1,350, whichever is lower |
| Foreign currency mark-up | 3.50% from 15 Jun 2026 (3.40% before that) |
| Dynamic currency conversion | 1% + GST when a foreign transaction is billed in rupees |
| Cash advance fee | 2.5% or ₹650, whichever is higher (from 15 Jun 2026) |
| Overlimit | ₹550 + GST per transaction above the limit (from 1 Jun 2026) |
| Rent | Up to ₹1,000: 1% or ₹1; above ₹1,000: 1% or ₹199, whichever is higher |
| Wallet loads | Free up to ₹2,000; 1% above that, max ₹5,000 per transaction |
| Education via third-party apps | 1% + GST, capped at ₹5,000 a month |
| Utility | 1% + GST on all utility transactions if the previous month’s utility spend crossed ₹25,000; max ₹5,000 per transaction |
| Card re-issue (lost/stolen/damaged) | ₹199 from 15 Jun 2026 |
| GST | 18% on all fees and charges |
The MITC also says cash withdrawal on a new YES BANK credit card is suspended for the first six months after onboarding. After that, the cash limit is a part of your credit limit, and cash advances attract interest from the day you withdraw. On fuel, the MITC lists a 1% + GST fee if a single fuel transaction is above ₹10,000 or if monthly fuel spend crosses ₹25,000 (capped at ₹5,000 per transaction). The bank also lists a 1% fuel surcharge waiver for POP-CLUB on transactions between ₹1,000 and ₹3,500, capped at ₹100 per statement cycle, from 1 June 2026. GST on the surcharge is not waived.
The big one for travellers is the 3.50% forex mark-up, plus 18% GST on the mark-up. If you shop on foreign websites or travel abroad, compare options in our zero forex markup credit card guide before you use POP-CLUB abroad.
Eligibility and how to apply
| What YES BANK lists | |
|---|---|
| Age | 21 to 60 years |
| Employment | Salaried or self-employed |
| Income | Minimum net salary of ₹25,000 a month, or an Income Tax Return of ₹7.5 lakh and above |
| Existing YES BANK cardholders | Not eligible for this card |
You apply through POP’s website or app, not a YES BANK branch form. The Apply Now button above opens POP’s application page through our partner network. Read the fee shown on your application screen carefully: that is where you will see whether you’re being offered the Lifetime Free version or the standard ₹399 schedule. Meeting the published criteria doesn’t guarantee a card. YES BANK decides approval and your credit limit, and the MITC says the variant offered depends on eligibility and the bank’s discretion.
Simple maths: does the fee pay for itself?
These examples only multiply the published earn rates. They count POPcoins, not rupees, because the bank doesn’t publish a rupee value per coin.
- ₹12,500 a month, all online: about 1,250 POPcoins a month, roughly 15,000 in a year. That is ₹1.5 lakh of yearly spend, so you also get the 1,500-coin milestone and the ₹399 renewal isn’t charged.
- ₹6,000 online + ₹4,000 UPI a month: about 600 + 80 = 680 POPcoins a month. That is ₹1.2 lakh a year, short of ₹1.5 lakh, so on the standard schedule you would pay ₹399 + GST and get 400 POPcoins back.
- ₹10,000 a month in rent and utilities: zero POPcoins, plus rent fees (₹199 + GST on a ₹10,000 rent payment, as the MITC’s own example shows). This card is the wrong tool for that spend.
The renewal fee is small. The bigger risk is interest: at 3.99% a month, a revolving balance wipes out a year of coins in no time. Pay the full bill by the due date, every month.
Who should get it and who should skip
- Good fit: people whose card spend is mostly online, who already buy from POPclub partner brands, and who want a RuPay card for UPI with no joining fee.
- Maybe: first-jobbers who meet the ₹25,000 net salary rule and want a low-cost starter card. Treat POPcoins as a bonus, not the reason.
- Skip: existing YES BANK credit cardholders (not eligible), frequent international spenders, and anyone whose spend is mostly rent, fuel, utilities, insurance or EMIs.
If your spend leans towards food delivery or Tata brands instead, read our Swiggy HDFC credit card benefits guide and the Tata Neu Plus vs Infinity comparison. The POP-CLUB product page we read lists no airport lounge benefit, so for lounges see our credit card for lounge access guide.
Frequently asked questions
Is the YES BANK POP-CLUB credit card lifetime free?
The joining fee is nil. YES BANK’s page advertises a limited-time Lifetime Free offer; cards issued under it don’t pay the annual fee. Otherwise the renewal fee is ₹399 + taxes, not charged if you spend ₹1.5 lakh in the anniversary year.
How many POPcoins does the POP-CLUB card give?
YES BANK lists 10 POPcoins per ₹100 on e-commerce/online spends and 2 POPcoins per ₹100 on other spends, including UPI. The minimum transaction is ₹100, and POPcoins are credited after the monthly statement is generated.
Do POPcoins expire?
Yes. YES BANK’s FAQ says POPcoins expire 365 days (one year) after the date they are credited.
What is the eligibility for the YES BANK POP-CLUB credit card?
Age 21 to 60, salaried or self-employed, with a minimum net salary of ₹25,000 a month or an ITR of ₹7.5 lakh and above. Existing YES BANK credit cardholders are not eligible. YES BANK decides approval.
Which spends don’t earn POPcoins?
Fuel, rent, wallet loads, government and marketing/advertising categories, ATM withdrawals, utility, insurance premiums, POI funding, EMI conversions and, from 1 June 2026, education transactions.
What is the forex mark-up on the POP-CLUB card?
YES BANK’s MITC lists a 3.50% foreign currency mark-up for POP-CLUB from 15 June 2026 (3.40% before that), plus 18% GST. Dynamic currency conversion attracts 1% + GST.
Sources (official pages, read 14 Nov 2026)
- YES BANK: POP-CLUB Credit Card product page (benefits, earn rates, Lifetime Free offer, eligibility, fees, FAQs, POPcoin exclusions and fuel waiver terms; read 14 Nov 2026)
- YES BANK: Credit Card Most Important Terms and Conditions (CMITC_V18_05102026) — POP-CLUB joining/annual fee and ₹1,50,000 waiver, finance charges, late payment, forex, cash advance, rent/wallet/utility/education/fuel fees, re-issue, fuel surcharge waiver (read 14 Nov 2026)
Info checked 14 Nov 2026, 3:55 pm IST. Every fee, reward rate, welcome benefit and eligibility rule on this page was read from the bank’s own website and documents (listed under Sources) at that time. Banks change card terms often, so the bank’s page when you apply is final. Card approval, credit limit and final terms are decided only by the bank. Nothing here is financial advice or a guarantee of approval or savings.
Disclosure
Some buttons on this page (like “Apply Now”) take you to a partner site through our partner network, Cuelinks. If you apply and the bank approves your card through them, GrabDeals may earn a small commission at no extra cost to you. It never decides what we write or which card we suggest. How we earn · How we pick
Keep exploring
Coupons today · Compare credit cards · Flights & hotels · All buying guides